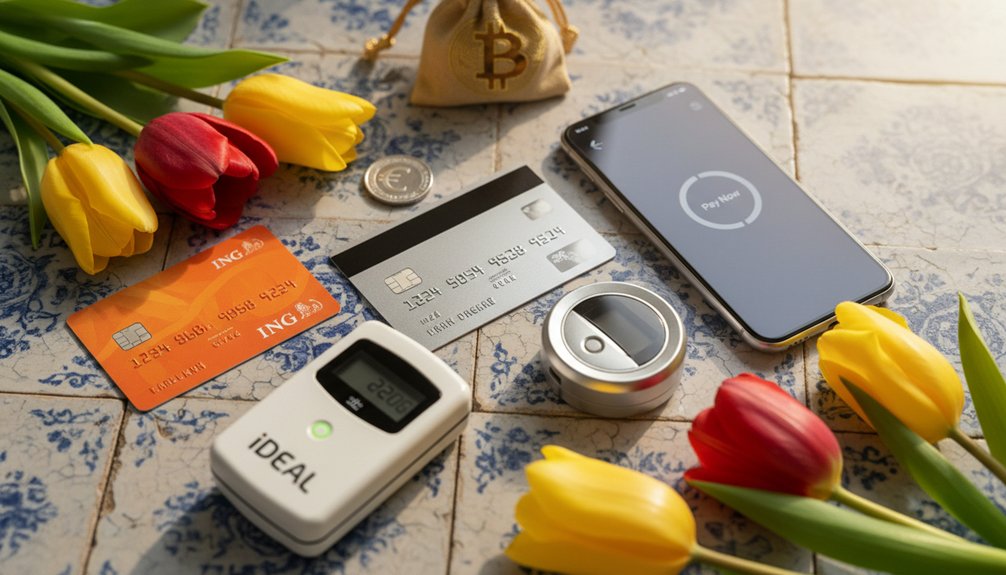
Your Dutch online shop should integrate seven essential payment options to boost sales effectively. Start with iDEAL, as 70% of Dutch shoppers rely on it for their purchases. Include major credit and debit cards to accommodate international customers. Add PayPal to provide buyer protection and enhance customer trust. Implement Buy Now Pay Later services like Klarna, Riverty, and in3 to attract customers looking for flexible payment solutions.
For Belgian customers, add Bancontact to your payment options. Incorporate SEPA Direct Debit for seamless transactions across European markets. Choose a PCI-compliant payment gateway such as Mollie, Adyen, or Stripe. These gateways support 3D Secure authentication, which protects you and your customers from fraud while ensuring compliance with security standards.
Make sure to avoid payment options that are less popular or not widely recognized in the Netherlands, as these could hinder sales. Focus on offering a streamlined checkout experience using these seven payment methods to optimize conversions and customer satisfaction.
iDEAL: Why 70% of Dutch Online Shoppers Won’t Buy Without It
When Dutch consumers reach the checkout page of an online store, they prioritize one payment method: iDEAL. iDEAL connects directly to a customer’s bank account, enabling instant transfers without the need for credit cards. Approximately 70% of Dutch shoppers refuse to complete purchases if iDEAL is unavailable. This preference arises from the Netherlands’ robust banking infrastructure and the cultural trust in direct bank payments.
Dutch consumers favor iDEAL because it provides real-time payment confirmation and enhanced security through bank-level authentication. Implementing iDEAL is essential for success in Dutch e-commerce.
Without iDEAL, online retailers risk losing a significant portion of potential customers who consider it their main payment method.
Credit and Debit Cards for International Customers
International customers primarily use credit and debit cards for online purchases. To effectively capture global sales, businesses must accept major card networks, including Visa, Mastercard, and American Express. These cards facilitate smooth transactions across borders, making them essential for reaching customers outside the Netherlands.
Accepting Visa, Mastercard, and American Express is essential for businesses seeking to capture global sales and reach international customers effectively.
When considering credit and debit card acceptance, businesses must account for international transaction fees. These fees typically range from 1% to 3% per transaction, which can significantly affect profit margins. Additionally, currency conversion rates can influence the final amount received when customers pay in their local currency.
To mitigate these costs, companies should partner with a payment processor that offers competitive rates and clear pricing structures.
Accepting credit and debit cards allows businesses to broaden their customer base. By providing familiar payment options, companies can cater to international shoppers who trust these methods. Ultimately, implementing card acceptance is a strategic move for businesses aiming to thrive in the global market.
PayPal: When Convenience Justifies the Higher Fees
PayPal justifies its higher transaction fees by providing robust transaction security and widespread global recognition. PayPal charges between 2.5% and 3.4% per transaction, alongside fixed fees. This pricing reflects the comprehensive buyer protection, fraud prevention measures, and instant payment processing that PayPal offers.
By using PayPal, your customers don’t need to share credit card details with your shop, which reduces your liability in case of fraud. PayPal also has a dispute resolution system that efficiently manages chargebacks, giving both merchants and customers peace of mind.
Alternatives like Mollie and Adyen may offer lower fees, but they often lack PayPal’s established trust among consumers worldwide. For Dutch shops aiming to attract international customers, PayPal’s convenience and brand recognition can outweigh the costs.
By accepting PayPal, you may attract more buyers who prefer familiar payment options, which can lead to increased conversion rates despite the higher transaction fees.
Klarna, Riverty, and in3: Adding Buy Now, Pay Later Options
Buy Now, Pay Later (BNPL) services like Klarna, Riverty, and in3 have changed how Dutch consumers approach online shopping. These services allow shoppers to break down their purchases into manageable installments.
Klarna offers flexible payment terms and a fast approval process. This combination increases conversion rates, especially among younger shoppers who prefer to spread out costs.
Riverty provides competitive transaction rates and includes robust fraud protection within its platform. Riverty also integrates effectively with most e-commerce systems.
In3 allows Dutch customers to pay in three equal, interest-free installments. This model reduces the risk of chargebacks because the BNPL providers assume the payment risk.
These BNPL options typically charge between 2-5% per transaction. However, they can increase your average order values by 30-50%.
To maximize your revenue, evaluate which provider best suits your target audience and aligns with your product pricing.
Bancontact and SEPA for Customers Across Belgium and Europe
If your business sells products or services to customers in Belgium and throughout Europe, you need to provide payment methods that align with their preferences. Bancontact serves as the primary payment system in Belgium, trusted by a majority of consumers. Offering Bancontact allows you to cater to local customers who favor using their bank accounts over credit cards for online transactions.
Additionally, implementing SEPA Direct Debit enables you to collect recurring payments directly from bank accounts across the European Union. This payment method is essential for businesses that rely on subscription models or want to simplify the payment process for their customers.
By integrating both Bancontact and SEPA Direct Debit, you can tap into a large market of potential customers who prefer these payment options. In Belgium alone, millions of consumers prefer bank-based payments, and this trend is consistent across several European countries.
Therefore, providing these payment methods not only increases customer satisfaction but also enhances your business’s reach and revenue potential. Furthermore, be aware of the VAT registration requirements to ensure compliance with local tax laws as you expand your payment options.
Keep in mind that while Bancontact is widely accepted in Belgium, it may not be as effective for customers located outside the country. Similarly, SEPA Direct Debit can facilitate payments across the EU, but it requires customers to authorize payments upfront.
Understanding these constraints will help you design a payment strategy that meets your business needs while satisfying customer preferences.
Bancontact Payment Processing Benefits
Belgian shoppers consistently choose Bancontact for their online transactions. Dutch online retailers aiming to tap into the Belgian market should adopt Bancontact as a payment method.
Bancontact provides instant payment confirmation. This feature minimizes transaction delays and enhances cash flow management. Additionally, Bancontact significantly lowers chargeback rates, as customers authenticate payments through their banking apps, which adds a layer of security.
Integrating Bancontact is straightforward with most payment service providers. Retailers can implement this payment option with minimal technical expertise. The checkout process becomes faster because Belgian customers connect directly to their bank accounts. They avoid entering card details manually, streamlining transactions and improving user experience.
Moreover, Bancontact offers competitive transaction fees compared to traditional credit card processing. Retailers can maximize their profit margins while effectively serving the Belgian market.
SEPA Direct Debit Features
Expanding your payment options to include SEPA Direct Debit allows your business to reach millions of customers across 36 European countries. This method withdraws funds directly from your customer’s bank account after they provide authorization, which makes managing recurring payments much easier.
| Feature | Description | Business Impact |
|---|---|---|
| Geographic Reach | SEPA works across 36 European countries | This significantly broadens your customer base. |
| Processing Time | Settlement takes 2-5 business days | This provides predictable cash flow management. |
| Cost Structure | Transaction fees are lower than card payments | This helps to reduce your operational expenses. |
| Authorization | A one-time mandate from the customer is required | This simplifies the process for repeat purchases. |
| Chargeback Period | Authorized payments have an 8-week chargeback period | This minimizes the risk of disputes. |
Understanding the advantages of SEPA Direct Debit helps your business serve European customers more effectively. However, be aware of its limitations. Processing times are longer compared to instant payment methods, and SEPA is only available within Europe.
Cross-Border Transaction Coverage
As your Dutch online shop grows into new European markets, you need reliable payment methods that facilitate cross-border transactions. For Belgian customers, use Bancontact, which allows for straightforward payments.
For broader coverage, implement SEPA Direct Debit, which services 36 European countries. These payment solutions directly address barriers that can limit international sales.
International transaction fees differ among payment providers. Analyze the fee structures carefully. Some payment processors charge flat rates, while others take a percentage of each transaction. Generally, SEPA Direct Debit offers lower fees compared to credit card transactions for European payments.
Consider how currency conversion rates affect your profit margins when accepting payments in various currencies. Opt for payment providers that offer transparent exchange rates without hidden fees.
By choosing gateways that allow you to accept euros throughout Europe, you simplify transactions, lower conversion costs, and foster trust with your international customers.
Plan your payment strategy by evaluating these options and their implications for your business operations.
Mollie vs. Adyen vs. Stripe: Choosing Your Payment Gateway
Which payment gateway serves your Dutch online shop best? Let’s compare three leading options: Mollie, Adyen, and Stripe.
Mollie supports local payment methods like iDEAL and Bancontact, making it a strong choice for Dutch merchants. Mollie offers transparent pricing and enables quick setup, which is essential for small to medium-sized businesses that want to start accepting payments without delays.
Adyen provides enterprise-level capabilities and advanced fraud detection. Adyen suits larger businesses that require a global reach and extensive payment options. However, its complex integration may not be the best fit for smaller shops that need straightforward solutions.
Stripe offers competitive fees at 1.4% plus €0.25 per European card transaction. Stripe includes excellent developer tools and comprehensive API documentation, making it a solid choice for businesses focused on scalability and customization.
All three payment gateways prioritize security through PCI DSS compliance and encryption.
Your decision should reflect the size and needs of your business: Mollie is ideal for small to medium shops; Adyen is tailored for high-volume enterprises; and Stripe balances scalability with user-friendly features.
PCI Compliance and 3D Secure: Security Requirements You Can’t Skip
When you accept online payments, you must adhere to two critical security standards: PCI DSS compliance and 3D Secure authentication. These standards protect your business and your customers from potential fraud.
PCI DSS compliance requires you to handle, process, and store cardholder data securely. For instance, you must encrypt transactions, maintain secure networks, and regularly monitor your systems for vulnerabilities. Most payment gateways streamline this process by managing PCI compliance on their secure servers, significantly reducing your workload.
PCI DSS compliance demands secure handling of cardholder data through encryption, network security, and continuous system monitoring to protect against vulnerabilities.
3D Secure authentication adds an essential layer of protection during the checkout process. For example, Dutch customers often verify their purchases using a banking app or SMS code. By implementing 3D Secure correctly, you can shift liability for fraudulent transactions from your business to the card issuer, minimizing your risk.
Both PCI DSS compliance and 3D Secure are non-negotiable. PCI standards ensure your business remains legally compliant, while 3D Secure helps prevent chargebacks and fosters customer trust in your online store.
Skipping these security measures can expose your business to legal penalties and financial losses.